UK Food & Grocery Sector Report summary
August 2026
Period covered: Period covered 05 July – 01 August 2026
3 minute read
Note: This report summary is one or two months behind the current month as standard reporting practice. The content is indicative only and incomplete with certain data undisclosed. Become a member to access this data or take out a free 30 day membership trial now.
Food & Grocery Sales
Food and grocery sales increased by xx% year-on-year in July, a small improvement on the xx% rise recorded in June, but below the xx% growth seen in the same month last year.
The result came as official food inflation slowed to xx% from xx% in June, its lowest rate since September 2021, providing further relief for households.
July also contained several reasons for consumers to spend, with the latter stages of the World Cup, Wimbledon and another month of exceptional temperatures supporting purchases associated with watching sport, entertaining and spending time outdoors.
Key trading themes and drivers
The combination of sport and exceptional heat had a considerable influence on shopping behaviour during July. Worldpanel recorded xx million grocery trips during the four weeks to 12 July, equivalent to around xx per household and the highest total since March 2020, while convenience stores received seven million more visits than during the comparable period last year.
England's progress through the World Cup gave supermarkets and convenience stores a succession of major viewing occasions during the first half of July.
Shopping trips containing beer or cider increased xx%, while beer expenditure around England's first three knockout matches was xx% higher than on the equivalent days in 2025. No and low-alcohol products also appeared in xx% more shopping trips, widening the benefit beyond conventional alcoholic drinks.
Another exceptionally warm month supported a much broader range of summer products, with soft drinks, ice cream, bottled water, burgers and frozen lollies among the areas benefiting from consumers spending more time outdoors.
NIQ recorded £xx of soft drink sales and £xx of ice cream sales in its later reporting period, with soft drinks, ice cream and suncare accounting for xx% of FMCG value growth.
Branded products also enjoyed a stronger month, growing xx% compared with xx% for own label, the first time brands had grown faster since August 2025. Much of this came from categories closely associated with summer and social occasion.
Promotional activity remained prominent, with around a quarter of FMCG sales purchased on promotion, showing that price still mattered even when consumers were prepared to spend more freely for particular occasions.
Competition between grocers remained intense with Lidl, recording the largest market-share gain among the major grocers over the 12 weeks to 12 July as sales increased xx%, while Ocado grew xx% and Morrisons returned to share growth. M&S grocery-only FMCG sales increased xx%, its fastest growth since May 2023.
Macroeconomic backdrop
Overall CPI inflation increased to xx% from xx% in June, while Ofgem's xx% increase in the energy price cap took effect on 1 July, adding £221 a year to a typical dual-fuel bill.
Households were paying less inflation on food at the same time as a larger proportion of income was being directed towards gas and electricity, limiting how much of the grocery saving became genuinely disposable income.
Borrowing costs remained elevated, with the Bank of England keeping Bank Rate at xx% in July, and mortgage pricing continued to affect households refinancing onto more expensive deals.
Grocery is less directly exposed to interest rates than big-ticket retail because food purchases cannot simply be postponed, but higher fixed household costs influence the choices consumers make once they enter a supermarket.
The labour market also became less comfortable, with payrolled employment estimated to have fallen xx year-on-year in July, unemployment standing at xx% in the three months to June and vacancies remaining around a five-year low.
Wage growth continued to exceed inflation, preserving growth in real earnings, but the gap had narrowed and households were still managing their spending against a backdrop of weaker employment conditions.
Consumer confidence provided a more encouraging support for households, rising six points to xx, its largest monthly improvement since November 2023. July's grocery behaviour showed consumers are prepared to loosen their budgets around football, hot weather and social occasions,
Take out a FREE 30 day membership trial to read the full report.
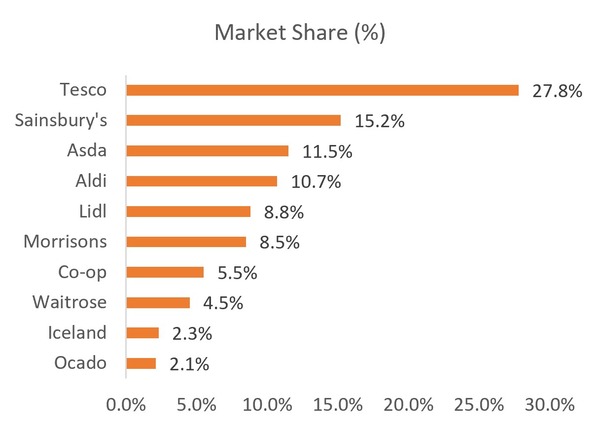
UK Grocery Market Share (12 weeks to 8 August)
 Source: Worldpanel, Retail Economics